Getting Your Portugal Tax Residency Certificate: What It's For and How to Request It
How to request a Portuguese tax residency certificate on Portal das Finanças, what it proves, and the rejection reasons that catch people out.
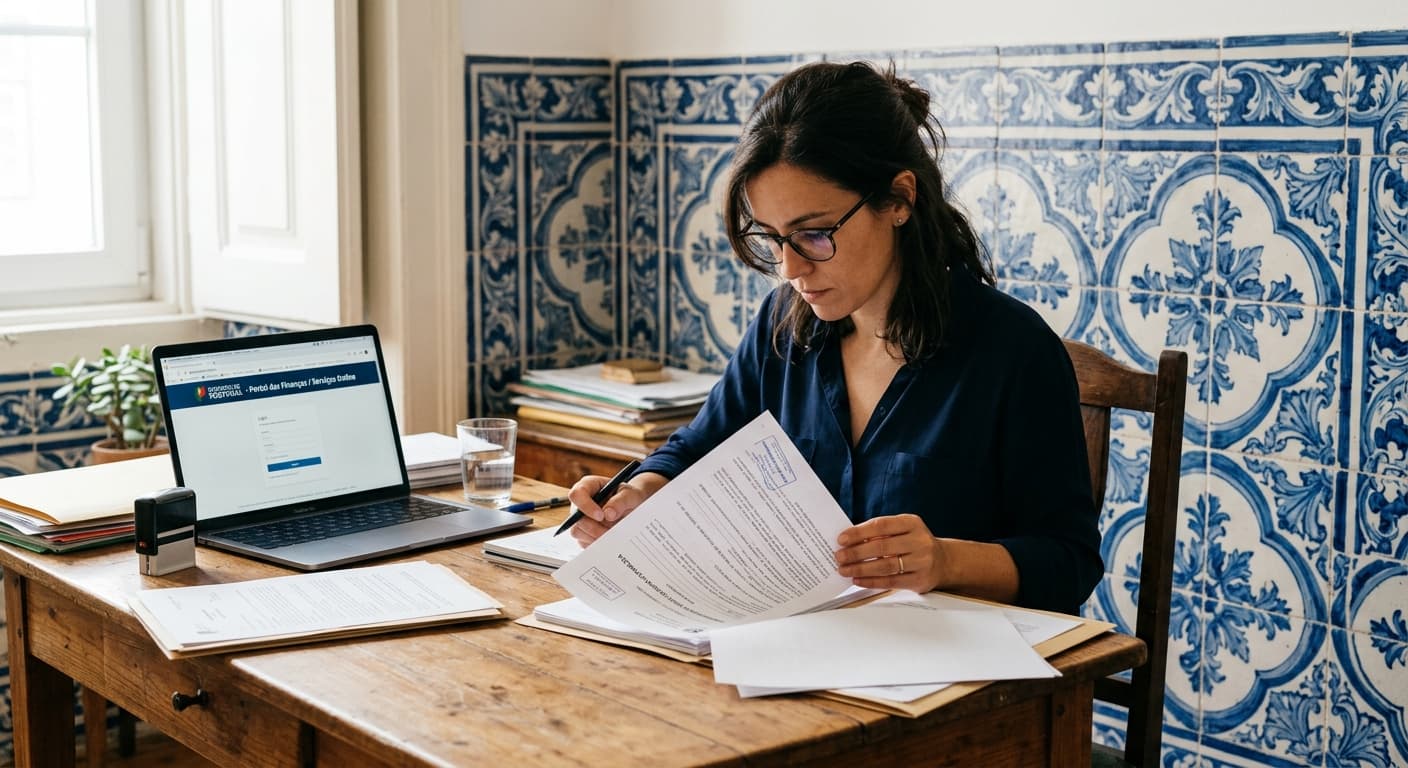
If a foreign bank, a pension provider, or a tax office abroad has asked you for "proof of tax residency" in Portugal, they almost certainly mean one specific document: the certidão de residência fiscal, issued by Portal das Finanças. Most guides treat this as a two-minute formality. In practice it's the document that decides whether you pay tax twice on the same income, whether a foreign bank will stop withholding tax at the full domestic rate, and whether your accountant can build a clean, audit-proof file if the AT or a foreign authority ever asks questions. Getting it right the first time matters more than the forms suggest.
What a Portuguese tax residency certificate actually proves
The certificate is Portugal's formal confirmation, issued by the Autoridade Tributária e Aduaneira (AT), that you were tax resident in Portugal for a specific period — usually a calendar year. It's not proof that you live here, that you have a visa, or that you're registered with your local council. It's a statement about tax status only: that for the year in question, Portugal considered you resident for tax purposes under its domestic rules and, where relevant, under a specific double taxation agreement.
That distinction matters. A NIF (tax number), a residence permit, or a utility bill in your name says nothing about tax residency on its own. Foreign institutions that ask for "proof of tax residency Portugal" are asking for this certificate specifically, because it's the one document the other country's tax authority will actually accept as evidence when applying a treaty.
Who typically needs one (and why)
We see requests cluster around a handful of situations:
- People receiving foreign-source pensions, dividends, interest, or royalties who want the paying country to apply a reduced withholding rate under the relevant Portugal double taxation agreement, rather than refunding the excess later.
- Foreign banks and brokers that require annual confirmation of tax residency to keep an account classified correctly for reporting purposes (including under automatic exchange of information rules).
- NHR and IFICI holders who need to demonstrate Portuguese tax residency alongside their special regime status, particularly when a foreign tax authority queries a treaty claim.
- Self-employed workers and remote employees who moved to Portugal mid-year and need to settle their residency status with a former home country's tax office.
- Anyone selling foreign property, disposing of crypto assets, or closing out rental income abroad who needs to show which country has primary taxing rights.
If you're not sure which of these applies to you, that's usually the first thing worth clarifying before you request anything — applying for a certificate you don't actually need, or for the wrong year, is one of the more common ways people waste a few weeks.
Step-by-step: requesting it on Portal das Finanças
The Portal das Finanças residency request is done entirely online, assuming your account access is already active. Broadly, the flow is:
- Log into Portal das Finanças with your NIF and password (or Chave Móvel Digital).
- Go to "Todos os Serviços" and search for "Certidões".
- Select the option for residência fiscal and choose the tax year you need the certificate for.
- If the certificate is for use in a specific country under a double taxation agreement, say so where the form allows it — some treaty partners expect a country reference on the certificate itself.
- Submit the request and wait for AT to process it. You'll be notified through your Portal das Finanças mailbox (Caixa Postal Eletrónica) rather than by regular email, so check that folder rather than your inbox.
- Once approved, download the certificate as a PDF directly from "Consultar Certidões" — it's generated automatically once processed and doesn't need to be collected in person.
The interface itself is straightforward. The part that trips people up is everything that has to be true before you click submit.
Documents and eligibility checks before you apply
Technically, you don't upload supporting documents for this request — AT checks its own records. But those records need to already reflect reality, which means a few things need to be sorted in advance:
- Your registered morada fiscal (tax address) on Portal das Finanças needs to match where you actually lived during the period in question.
- Your tax return (Modelo 3) for that year generally needs to have been submitted, since AT uses it to confirm residency status.
- Any special regime — NHR, IFICI, or otherwise — needs to be correctly registered against your NIF, not just assumed.
- You shouldn't have outstanding tax debts or unresolved notices flagged on your account, since these can delay or block certificate issuance entirely.
This is the point where it helps to actually check your situation against the rules rather than assume it's fine — particularly if you split time between Portugal and another country during the year, or changed regime partway through. We built our assistant specifically for this kind of check: it looks at your residency facts, income types, and regime, and flags where the eligibility conditions in Portuguese law and AT guidance might not line up with what's on file — before you find out the hard way through a rejection.
Processing time, validity, and renewals
Processing isn't instant, and there's no guaranteed turnaround — it depends on AT's workload and whether anything on your file needs manual review. Build in a buffer rather than requesting it the week before a deadline. The certificate itself is tied to a specific year; it doesn't expire in the way a passport does, but many foreign institutions will only accept one issued relatively recently, so you'll typically need to request a fresh one each year rather than reuse an old copy. If your circumstances change — a change of regime, a change of address, a dispute over your residency status — you'll need a new certificate reflecting the corrected position, not an amendment to the old one.
Using the certificate to claim double taxation treaty relief
This is where the document earns its keep. Portugal has a wide network of double taxation agreements, and most of them rely on exactly this certificate to establish which country has the right to tax a given item of income, or at what reduced rate. A foreign payer of dividends, interest, or a pension will typically ask for this certificate before applying the treaty rate at source, rather than the full domestic withholding rate with a refund claim afterwards — the former is faster and avoids tying up your money for months.
Some countries want the certificate attached to their own specific treaty relief form rather than submitted alone, so it's worth checking what the paying country's tax authority actually requires before you request the Portuguese side. Submitting the wrong format, or a certificate for the wrong year, is a common reason these claims bounce back for correction.
Common rejection reasons and how to avoid them
From what we've seen, requests get rejected or delayed for a narrow set of recurring reasons:
- The tax address on file doesn't match the address implied by the year's tax return, or by immigration records.
- No Modelo 3 was filed for the year requested, or it was filed late and hasn't finished processing.
- The person was only resident for part of the year and requested a certificate covering the full year without qualifying for it.
- A pending tax debt or an open query on the account blocks issuance until it's resolved.
- NHR or IFICI status wasn't properly registered at the time, so the certificate doesn't reflect the regime the person expected it to confirm.
Most of these are avoidable with a quick check beforehand rather than a dispute afterward. If you want a second opinion on whether your residency facts actually support the certificate you're about to request, that's exactly the kind of question our assistant is built to answer, with the specific rule or AT guidance behind the answer — not a generic summary.
How this fits with your annual tax return timeline
The certificate and your annual return are connected but separate obligations. Portugal's income tax return (Modelo 3) for a given year is generally filed between April and the end of June of the following year, and your eligibility for a residency certificate for that year depends on that return being filed and processed. If you're also navigating Portugal's income tax brackets for the first time, working out which regime applies, or reconciling foreign income with a treaty claim, it's worth getting the residency certificate request and the return itself sequenced correctly rather than treating them as unrelated admin. A structured note summarising your residency status, income sources, and regime — the kind we generate for accountant consultations — is often the fastest way to make sure both the certificate and the return line up before either gets submitted.